For generations, the mortgage has played a major role in making homeownership possible for millions of Americans. Instead of requiring buyers to pay for a home upfront, long-term mortgage financing allows the cost to be spread over many years.
That simple change helped transform homeownership from something available mainly to wealthier households into a realistic goal for many working families.
Today, however, buyers face a different challenge: higher home prices, changing mortgage rates, and affordability concerns.
Understanding how mortgages work—and how financing affects the total cost of a home—is more important than ever.
How Mortgages Changed Homeownership
Before long-term mortgage financing became widespread, purchasing a home often required a much larger upfront payment and shorter repayment periods.
The development of longer-term mortgages changed that equation. Buyers could use their future income to pay for a home over time rather than needing the full purchase price immediately.
The expansion of mortgage financing, combined with increased home construction and economic growth, helped expand homeownership across America. According to the source analysis, the U.S. homeownership rate rose from approximately 46% in 1900 to 66% by 2000.
Why Mortgages Still Matter Today
A mortgage isn't simply a way to buy a house. It can also influence how much home a buyer can comfortably afford.
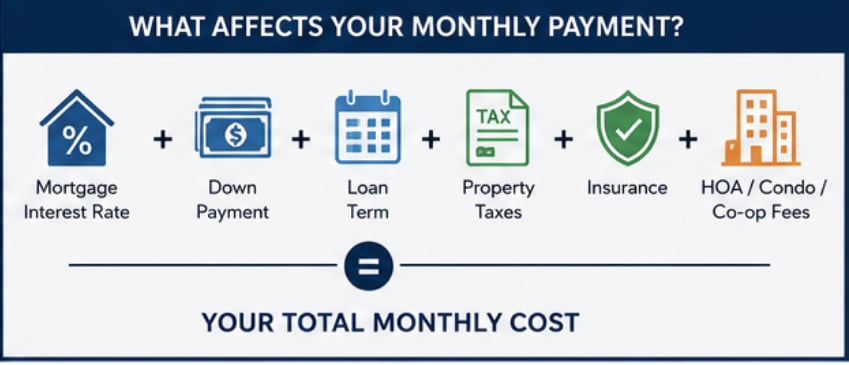
Two buyers purchasing the same property can have very different monthly payments depending on:
- Mortgage interest rate
- Down payment
- Loan term
- Property taxes
- Insurance
- HOA, condo, or co-op fees
That's why buyers shouldn't focus only on the purchase price.
The better question is: What will this home cost me every month?
What This Means for Today's NYC Buyers
For buyers in Flushing, Bayside, Whitestone, Fresh Meadows, Little Neck, Douglaston, College Point, Kew Gardens, Forest Hills, Rego Park, Jackson Heights, Elmhurst, Woodside, Astoria, and Long Island City, financing decisions can vary significantly depending on the property and neighborhood.
A single-family home, condo, or co-op may have completely different monthly expenses even when their purchase prices are similar.
Before making an offer, buyers should consider the complete cost of ownership—not just the mortgage payment.
Smart steps for buyers:
- Get pre-approved before seriously shopping.
- Compare mortgage options and lenders.
- Calculate your complete monthly housing cost.
- Keep emergency savings after closing.
- Consider how long you plan to own the property.
- Don't automatically borrow the maximum amount a lender approves.
Can Homeownership Still Build Wealth?
For many homeowners, yes.
As mortgage principal is paid down, homeowners can build equity. If the property appreciates over time, that can further increase household wealth.
However, homeownership also comes with property taxes, maintenance, insurance, closing costs, and other expenses. Buying a home should therefore be viewed as a long-term financial and lifestyle decision, not simply a bet on rising prices.
Frequently Asked Questions
Is a lower mortgage rate always better?
A lower rate generally reduces borrowing costs, but falling rates can also bring more buyers into the market. If inventory remains limited, increased demand may put upward pressure on home prices.
Should I wait for mortgage rates to fall?
There's no guaranteed way to predict future rates. Buyers should consider their finances, monthly affordability, local inventory, and long-term plans rather than trying to perfectly time the market.
Does this apply to NYC real estate?
Absolutely. NYC buyers need to consider mortgage costs along with property taxes, maintenance, condo fees, co-op maintenance, and other ownership expenses.
The Bottom Line
The history of the mortgage shows how financing helped make homeownership accessible to millions of Americans. Today, mortgages remain one of the most important factors determining whether a home fits a buyer's budget.
For today's buyers, the goal shouldn't necessarily be finding the perfect rate or waiting for the perfect market.
It's finding the right property and financing strategy for your financial situation and long-term goals.
Your Local Real Estate Resource
June Chang | JuneNYC Team
www.JuneChangNYC.com
Queens & NYC Seller Agent
Helping clients buy, sell, and rent in Flushing, Bayside, Whitestone, Astoria, LIC, and throughout NYC.
Speaks Chinese (Mandarin & Taiwanese).
Contact June Chang: 917-657-5198